The price snapshot
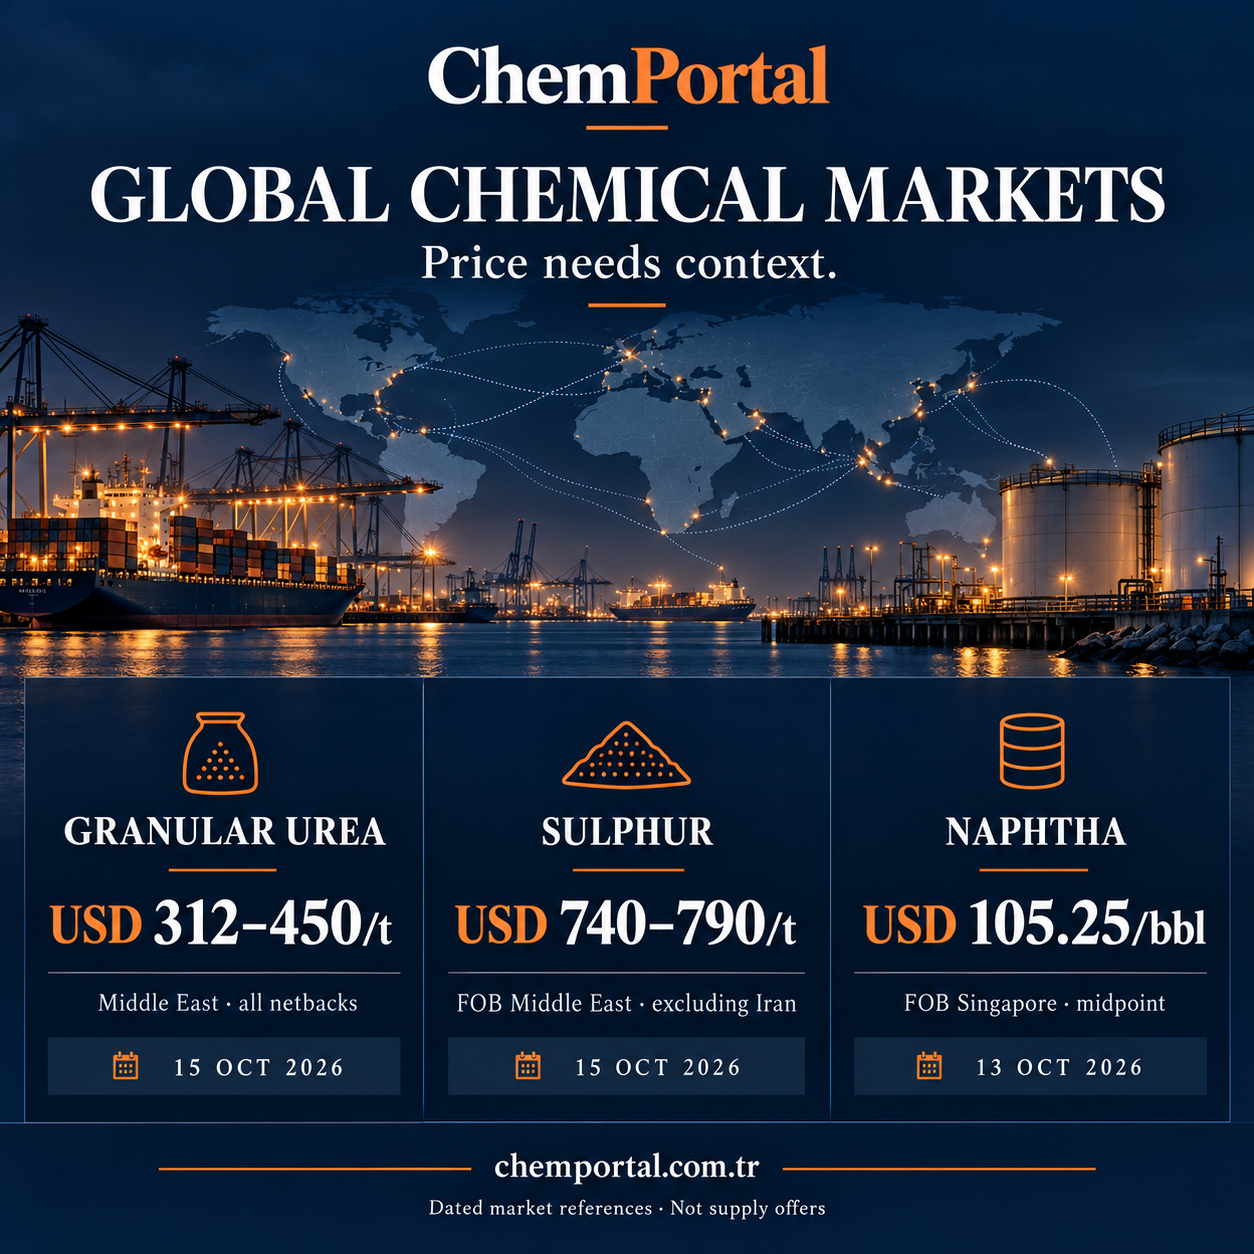
Granular urea
Middle East · all netbacks · FOB
Both endpoints rose in the physical granular table. An all-netback range is not a single offer, and its lower end is not evidence of material available for purchase.
Read the urea tables and freight contextSulphur
FOB Middle East · excluding Iran
The spot range softened. Keep it separate from quarterly contract markers and delivered assessments; a lower FOB reference alone does not establish a lower landed cost.
Explore sulphur spot prices and routesNaphtha
FOB Singapore · midpoint
The reported range is 105.23–105.27 USD/barrel. This Singapore midpoint is not interchangeable with a Japan delivered or Persian Gulf per-tonne assessment.
See the regional fuel and naphtha benchmarkst = metric tonne; bbl = barrel. The newsletter date does not update the assessment dates. These references are neither live quotations nor supply offers.
The global context
Energy recovery is not moving in a straight line.
In its 14 October 2026 Oil Market Report, the IEA forecasts weaker global oil demand in 2026 while still expecting an oil-market deficit through year-end. It also describes freight and crude costs squeezing refinery margins in Europe and Asia. Read the IEA report.
Our reading: A softer naphtha snapshot is not, by itself, proof that feedstock or transport conditions have normalised. Demand, refinery economics and shipping can send different signals.
Fertilizer exposure extends far beyond one region.
FAO's 2026 technical brief links disruptions to energy and fertilizer trade with risks to farm input costs and food production, particularly in import-dependent parts of Africa and Asia. This is broader 2026 context, not a new October price assessment. Read the FAO brief.
Our reading: Follow regional production, trade access and freight alongside the headline urea or sulphur number. These broader reports do not establish the cause of any individual price move above.
Before comparing two prices
- Match the product. Granular and prilled urea are separate assessment sets.
- Keep the date and period. Physical, October and front-month references are not the same series.
- Check units and delivery. USD/t, USD/st and USD/bbl are not interchangeable. CFR already includes freight; do not add it twice.
Follow the market, with context.
Explore the dated tables, regional assessments and freight references on ChemPortal.
Explore the market reportsReferences and reading notes
Market references: the linked ChemPortal tables, checked 20 October 2026. External material: IEA, published 14 October 2026, and FAO's 2026 technical brief, accessed 20 October 2026. Summaries and the explicitly labelled editorial interpretation are separate; no affiliation or endorsement is implied.
For market information only. Not investment advice, a live quotation, confirmation of availability, or a commitment to supply or deliver any product.